The SARS Penalty Trap: How R100,000 in Monthly Payroll Becomes R125,000 Overnight
It is 16:30 on Friday, the 7th of the month.
You’ve spent the week negotiating supplier contracts, chasing late client invoices, and keeping your operations moving forward. Payroll went out on time, your team is happy, and you tell yourself you’ll submit the EMP201 and transfer the withheld PAYE, UIF, and SDL to SARS first thing on Monday morning. What difference could two days make?
To the South African Revenue Service, those two days change everything.
By Monday morning, an automated administrative penalty triggers across your account. What began as a minor scheduling slip quickly escalates into a compounding financial burden that drains cash flow and damages your standing with tax authorities.
Here is how small, easily overlooked payroll filing mistakes quietly cost South African businesses tens of thousands of Rands—and how to safeguard your company from the SARS penalty trap.
The Math Behind the Trap: A R100,000 Scenario
Consider a growing boutique agency or logistics provider with a monthly payroll liability of R100,000 (encompassing PAYE tax withholdings, 1% SDL, and 1% employer UIF contributions).
When the 7th deadline passes without payment and submission:
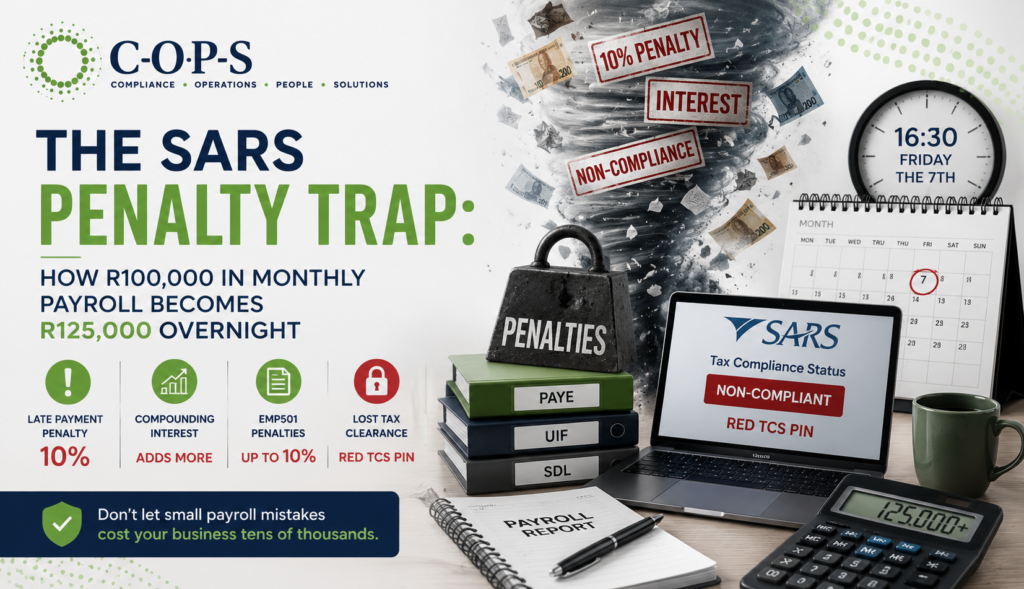
- Immediate 10% Late Payment Penalty: SARS applies an automatic, flat 10% penalty on the total outstanding amount the moment the cut-off passes. Your liability instantly increases by R10,000.
- Compounding Prescribed Interest: Interest immediately begins accruing on the unpaid amount (principal plus penalty) at the SARS prescribed interest rate.
- The EMP501 Reconciliation Stacking: If the monthly discrepancy remains unresolved by bi-annual reconciliation season (EMP501), SARS can impose non-compliance administrative penalties ranging from 1% up to 10% of your total annual PAYE liability.
- Lost Tax Clearance: Your Tax Compliance Status (TCS) pin turns red instantly. In South Africa, a red TCS pin blocks corporate tender bids, stalls enterprise contract renewals, and prevents bank credit facility approvals until cleared.
Within a single quarter of uncorrected delays, a R100,000 monthly liability easily expands into R125,000+ in total owed funds—R25,000 handed over in dead-weight penalties that deliver zero return to your business.
Beyond the Deadline: 3 Subtle Compliance Mistakes That Trigger Audits
Missing the 7th isn’t the only trigger for unexpected SARS interest and penalties. Three statutory details frequently catch South African business owners off guard:
1. The UIF Salary Ceiling Oversight
UIF is calculated at 1% from the employee and 1% from the employer, but contributions are strictly capped at a gross remuneration ceiling of R17,712 per month (a maximum contribution of R177.12 per side). Manual spreadsheet calculations often apply a flat 1% across an entire high-earning salary, causing incorrect tax certificates (IT3a/IRP5) during bi-annual reconciliations that require manual SARS correction.
2. Miscalculating the BCEA Earnings Threshold
The Department of Employment and Labour sets the Basic Conditions of Employment Act (BCEA) earnings threshold (updated to R269,600.90 per year / R22,466.74 per month). Employees earning below this threshold have statutory rights to strict overtime, Sunday pay, and night shift allowances. Misclassifying employees across this threshold leads to incorrect gross remuneration figures, distorting your statutory PAYE and SDL calculations.
3. Using Retained Tax Funds as “Short-Term Working Capital”
When cash flow tightens, some founders fall into the trap of using withheld PAYE and UIF funds to pay pressing supplier invoices, intending to replace the cash before month-end. Under Schedule 4 of the Income Tax Act, failing to pay over deducted PAYE to SARS is a direct statutory violation that carries personal liability for company directors.
3 Actionable Steps to Lock Down Your Payroll Compliance
- Establish an Automated “3rd-of-the-Month” Cut-Off: Never aim for the 7th. Set your internal processing deadline for the 3rd of every month to allow a 48-hour buffer for bank clearing delays or public holidays.
- Segregate Statutory Tax Accounts: Create a dedicated, ring-fenced bank account for monthly tax withholdings. As salaries are paid, transfer the corresponding PAYE, UIF, and SDL amounts out of your main operating account immediately.
- Transition from Manual Spreadsheets to Integrated Systems: Modern cloud payroll software automatically updates SARS tax tables, enforces UIF ceiling caps, and generates pre-validated EMP201 files directly linked to eFiling.
Turn Compliance into Your Competitive Advantage
Clean, predictable bookkeeping isn’t just about avoiding SARS fines—it gives you an unobstructed view of your true operating margin, protects your commercial reputation, and frees up mental energy to focus on strategy and scaling.